


Текст на Статията
- Пързалка: 1
- Let’s focus on the climate risks affecting the seaside plant.
- I’ve got the impairment checklist ready.
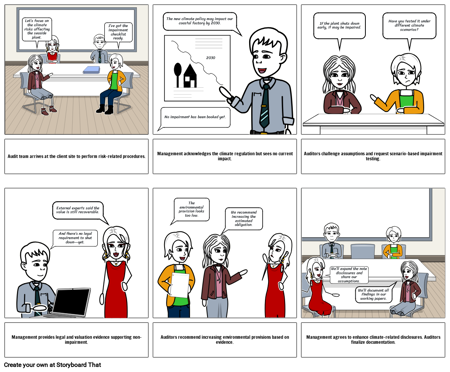
- Audit team arrives at the client site to perform risk-related procedures.
- Пързалка: 2
- The new climate policy may impact our coastal factory by 2030.
- 2030
- No impairment has been booked yet.
- Management acknowledges the climate regulation but sees no current impact.
- Пързалка: 3
- Have you tested it under different climate scenarios?
- If the plant shuts down early, it may be impaired.
- Auditors challenge assumptions and request scenario-based impairment testing.
- Пързалка: 4
- External experts said the value is still recoverable.
- And there’s no legal requirement to shut down—yet.
- Management provides legal and valuation evidence supporting non-impairment.
- Пързалка: 5
- The environmental provision looks too low.
- We recommend increasing the estimated obligation.
- Auditors recommend increasing environmental provisions based on evidence.
- Пързалка: 6
- We’ll expand the note disclosures and share our assumptions.
- We’ll document all findings in our working papers.
- Management agrees to enhance climate-related disclosures. Auditors finalize documentation.