

Untitled Storyboard


Text z Príbehu
- Šmykľavka: 1
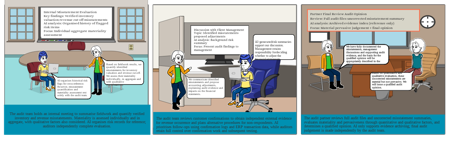
- Internal Misstatement EvaluationKey findings: Verified inventory valuation revenue cut-off misstatementsAI analysis: Organised history of flagged risk itemsFocus: Individual aggregate materiality assessment
- Based on fieldwork results, we quantify identified misstatements for inventory valuation and revenue cut-off. We assess their materiality individually, in aggregate and with qualitative considerations.
- The audit team holds an internal meeting to summarise fieldwork and quantify verified inventory and revenue misstatements. Materiality is assessed individually and in aggregate, with qualitative factors also considered. AI organises risk records for reference; auditors independently complete evaluation.
- Šmykľavka: 2
- Discussion with Client ManagementTopic: Identified misstatements proposed adjustmentsAI analysis: Background risk summaryFocus: Present audit findings to management
- The audit team reviews customer confirmations to obtain independent external evidence for revenue occurrence and plans alternative procedures for non‑respondents. AI prioritises follow‑ups using confirmation logs and ERP transaction data, while auditors retain full control over confirmation work and subsequent testing.
- Šmykľavka: 3
- Partner Final Review Audit OpinionReview: Full audit files uncorrected misstatement summaryAI analysis: Archived evidence index (reference only)Focus: Material pervasive judgement + final opinion
- We have fully documented the misstatements, management discussions and supporting audit evidence, and the basis for the qualified opinion will be appropriately described in the auditor’s report.
- The audit partner reviews full audit files and uncorrected misstatement summaries, evaluates materiality and pervasiveness through quantitative and qualitative factors, and determines a qualified opinion. AI only supports evidence archiving; final audit judgement is made independently by the audit team.
- Šmykľavka: 0
- We communicate identified misstatements and propose accounting adjustments, explaining audit evidence and impacts on the financial statements.
- AI-generatedrisk summaries support our discussion. Management retains responsibility fordeciding whether to adjust the financial statements.
- Based on quantitative and qualitative evaluation, these uncorrected misstatements are material but not pervasive. We will issue a qualified audit opinion.
- AI organises historical risk flags for cross-reference. However, misstatement quantification and materiality assessment rest solely with the audit team.